A car’s age can complicate financing, but it doesn’t automatically close the door. Understanding how to get a loan for a car over 10 years old starts with looking beyond standard auto-loan criteria: traditional lenders may decline older vehicles, while lenders experienced with classic or older cars may assess the vehicle and borrower differently. Mileage, condition, value, and your credit profile can all shape the options.
It’s reasonable to expect extra scrutiny when the car has decades of character and more miles behind it. The key is finding a financing route that fits both the vehicle and your circumstances, rather than assuming a conventional loan is the only path. This guide explains where older-car loans may be available, when classic cars can qualify, and what lenders typically consider during an application. You’ll also see how a specialist can help make the process clearer, from assessing a vehicle’s suitability to understanding the financing structure before you move ahead.
Key Takeaways
- Compare an auto loan with a personal loan, weighing the different interest-rate trade-offs and how each option is secured.
- Consider how a vehicle’s expected lifespan can influence the length of a loan and the repayment structure.
- Classic cars may qualify for specialist financing; age and mileage are among the factors that can affect approval.
- Understand how a lender may assess the vehicle, your credit profile, and the application details before choosing a financing path.
How can I get professional help financing an older car?
Specialist financing can help match an older vehicle with a suitable loan option. Lenders typically consider the car’s age and mileage alongside your credit profile.
Financing Older and High-Mileage Vehicles
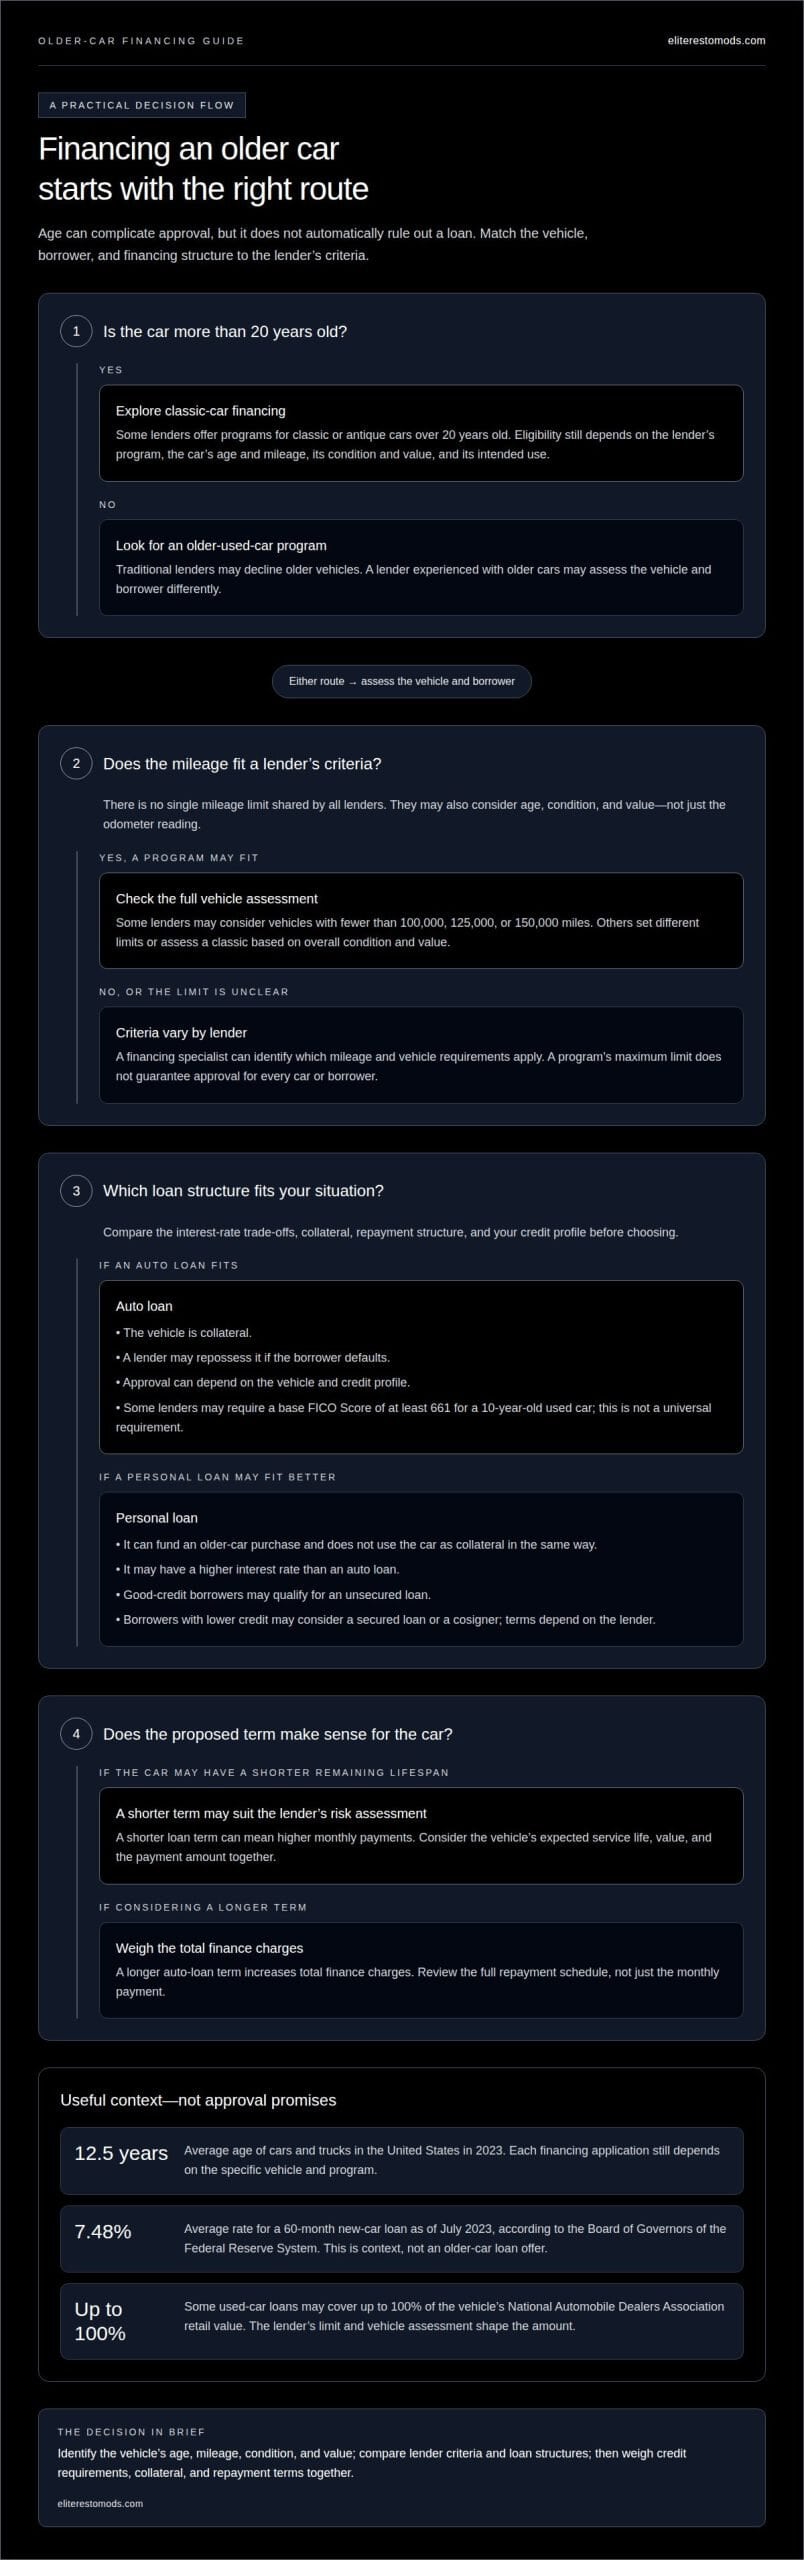
For a used car with high mileage, lenders may focus on its age, odometer reading, condition, and value. Some may consider vehicles with fewer than 100,000, 125,000, or 150,000 miles, while others set different limits. A financing specialist can identify which criteria apply to the vehicle and organize the application around the lender’s requirements. That matters when a well-kept car’s mileage tells only part of its story.
Challenges of Financing Older Cars
Older vehicles can be harder to finance because lenders may see greater mechanical risk and less predictable resale value. These concerns can affect approval and the interest rate, so a rate for a newer car is not a reliable forecast for an older one. As of July 2023, the average rate for a 60-month new-car loan was 7.48%, according to the Board of Governors of the Federal Reserve System. Use that figure as context, not as an older-car loan offer.
Classic and Antique Car Financing
Classic and antique cars may qualify through lenders that specialize in older vehicles, including cars more than 20 years old. The right route depends on the vehicle’s age, mileage, value, and intended use. A specialist can help align the financing request with those factors, rather than treating a collectible vehicle like an ordinary used car. For a distinctive model, its condition and market value can be central to the lender’s assessment.
A personal loan can also fund an older-car purchase. Borrowers with good credit may qualify for an unsecured personal loan; those with lower credit may consider a secured loan or a cosigner. Personal loans may have higher interest rates than auto loans, but they don’t use the car as collateral in the same way. Compare the full terms, repayment structure, and any collateral obligations before choosing.
Where can you get professional help with a loan for a car older than 10 years?
A borrower researching how to get a loan for a car over 10 years old can look to lenders with programs for older vehicles. Bad or no credit doesn’t automatically end the search: some borrowers may use collateral or a cosigner for a personal loan, though terms depend on the lender.
Vehicle Lifespan and Loan Terms
A lender’s estimate of a vehicle’s remaining lifespan can influence its repayment term. If the car may have limited service life or declining value, a shorter loan term may fit the lender’s risk assessment. Shorter terms can mean higher monthly payments. The average age of cars and trucks in the United States reached 12.5 years in 2023, but each application still depends on the specific vehicle and financing program.
Credit Approval and Vehicle Collateral
Credit history and vehicle details both inform approval. Some lenders may require a base FICO Score of at least 661 to finance a 10-year-old used car. With a secured auto loan, the vehicle is collateral, and a lender may repossess it if the borrower defaults. If the car is located in Michigan, include that location in the financing inquiry because geographic eligibility can depend on the lender’s program.
For someone considering how to get a loan for a car over 10 years old, credit approval and collateral requirements are key parts of the financing assessment. A personal loan can have a different structure from an auto loan, so the borrower’s credit profile and available collateral help determine which route may fit.
Loan Amounts and Vehicle Value
The amount a lender is willing to finance may be tied to the vehicle’s assessed value. Some used-car loans may cover up to 100% of the vehicle’s National Automobile Dealers Association retail value. The car’s value and the lender’s maximum help define a realistic loan request.
Do you finance classic cars?
Yes. Some lenders offer financing for classic or antique cars more than 20 years old. Approval still depends partly on the vehicle’s age and mileage, along with the lender’s program criteria.
Age and Mileage Effects on Approval
Age and mileage help lenders assess a vehicle’s condition, value, and expected lifespan. A low-mileage car may present a different risk from a heavily driven example of the same model year, but mileage alone doesn’t determine approval. Lenders consider the two together. For instance, an older coupe with documented low mileage may be assessed differently from a similar car with extensive use.
Model Year and Mileage Eligibility
Eligibility depends on how a lender defines a classic or antique vehicle and which model years its program accepts. Some lenders may finance classic cars more than 20 years old, but that age threshold doesn’t mean every qualifying-year vehicle is eligible. Mileage limits can also vary. A specialist can identify applicable program criteria and match the request to the car’s model year and odometer reading.
Vehicle Age and Mileage Requirements
There isn’t one age or mileage requirement shared by every lender. Some set odometer limits for used vehicles, while others may assess a classic based on its overall condition and value. A program’s maximum limit is not an approval amount for every car or borrower.
The requested loan term also affects affordability. A longer auto-loan term increases total finance charges, while a shorter term can raise the monthly payment. For a classic vehicle, weigh the proposed payment against the car’s value and the full repayment schedule. Matching the term to the vehicle and your budget helps keep financing practical, not just attainable.
How a professional handles an older-car loan application
A professional starts by matching the vehicle and borrower to suitable financing criteria. They review the car’s age, mileage, value, purchase details, and the borrower’s credit situation. This first assessment helps determine whether a purchase loan, refinancing, or cash purchase deserves attention. It also identifies factors that could affect approval before the application moves forward.
For a purchase loan, the financing professional organizes the relevant details into a clear application. Vehicle information and the requested loan amount help a lender assess the collateral and decide whether the proposed terms fit. The borrower’s credit profile also matters. For bad or no credit, some lenders may require a down payment of at least $1,000 or 10% of the vehicle’s purchase price, whichever is higher.
Paying cash is another option. Set a purchase budget based on the funds available, then decide whether you need to borrow for any remaining amount. Paying cash avoids an auto-loan application and monthly payments, but uses funds that might otherwise be available for other needs. If your planned purchase depends on borrowing, specialist financing can help you understand the available options.
Refinancing can be an option for an older vehicle that already has a loan. Some lenders may require the car to have fewer than 100,000 to 125,000 miles. They may also require the payoff balance to be between $3,000 and $7,500. The lender assesses the vehicle and existing loan against its refinancing criteria, so a car that qualified for its original loan may not automatically qualify again.
Application timing matters, too. A hard credit check for refinancing may cause a temporary dip in the borrower’s credit score. The professional can explain where that check fits in the process and help the borrower understand the requested terms before proceeding. For guidance tailored to a classic-car purchase, explore financing options.
Elite Restomods
Elite Restomods can help connect your financing decision with the classic vehicle you want to own. Its Elite Certified Restomods are investment-grade vehicles prepared for confident driving. If you have a specific vision, Custom Build Services can help bring it to life. The Consignment Program is an option if you’re looking to sell a classic vehicle.
Turn to Elite Restomods when you’re exploring a restomod, planning a custom build, or considering consignment as part of your ownership or selling plans. The right vehicle is more than a model year or mileage figure. It’s a considered choice about the experience you want on the road.
Contact Elite Restomods to discuss your classic-car plans.
Shape a financing plan around the car you want
Start by defining what ownership should look like: a particular marque, a distinctive driving experience, or a car tailored to your vision. Let that goal guide your financing conversation. Knowing what vehicle you want can help keep your search and funding decision aligned.
For anyone considering how to get a loan for a car over 10 years old, the right path begins with matching the financing approach to the intended vehicle and purchase. Elite Restomods offers Elite Certified Restomods, Custom Build Services, and a Consignment Program, connecting different classic-car goals with relevant offerings. Whether you’re pursuing a finished restomod, envisioning a bespoke build, or considering a classic through consignment, keep the ownership plan at the center of your next decision. The aim is more than securing a vehicle. It’s making a considered choice you’ll be proud to drive.
Contact Elite Restomods today to discuss your plans and take the next step toward the right classic car.
Frequently Asked Questions
Can I finance a car over 100,000 miles?
Yes, a car with more than 100,000 miles may still qualify, depending on the lender’s mileage ceiling. For example, a vehicle at 110,000 miles would exceed a 100,000-mile limit but fall below limits of 125,000 or 150,000 miles. Lenders also consider the car’s age, value, and condition, so mileage alone doesn’t decide eligibility.
Financing a 10-Year-Old Car: Can I Do It?
Yes, financing a 10-year-old car is possible through lenders whose programs accept that model year. Before submitting an application, identify the car’s exact year, mileage, and purchase details. These specifics help establish whether a lender’s vehicle criteria fit the car. If a standard auto loan isn’t suitable, a personal loan may be another route, with different terms and collateral arrangements.
What Is the Oldest Car That I Can Finance?
There isn’t one maximum age that applies across all financing programs. Some lenders offer financing for classic or antique vehicles more than 20 years old, while other programs focus on used cars with different age and mileage criteria. A car’s eligibility depends on the type of loan and its program rules. A classic-car financing specialist can help identify a suitable route for a particular vehicle.
What would my auto payments be?
Your monthly payment depends on the amount financed, interest rate, repayment term, and any down payment. For a useful estimate, calculate the payment using the amount you expect to borrow and the actual terms offered. Taxes, title, and licensing can affect the total purchase amount if they’re included in the financing. The lender’s final offer sets the payment schedule.
Which lenders offer auto loans for cars over 10 years old?
Specialist classic-car lenders may finance older vehicles. Elite Restomods’ Classic Car Financing works with Woodside Credit, JJ Best, and Collector Car Lending. Each lender sets its own criteria for the vehicle and borrower, so working with a financing partner doesn’t guarantee that every car or application will qualify. The car’s age, mileage, value, and requested loan structure all matter.
What are the age and mileage limits for used-car loans?
Limits vary by lender and loan type. Some used-car programs may accept vehicles with fewer than 100,000, 125,000, or 150,000 miles. Refinancing can have separate odometer criteria, with some lenders requiring fewer than 100,000 to 125,000 miles. Treat these as program-specific thresholds, not universal cutoffs. A lender assesses the vehicle’s model year and mileage against its own eligibility rules.